
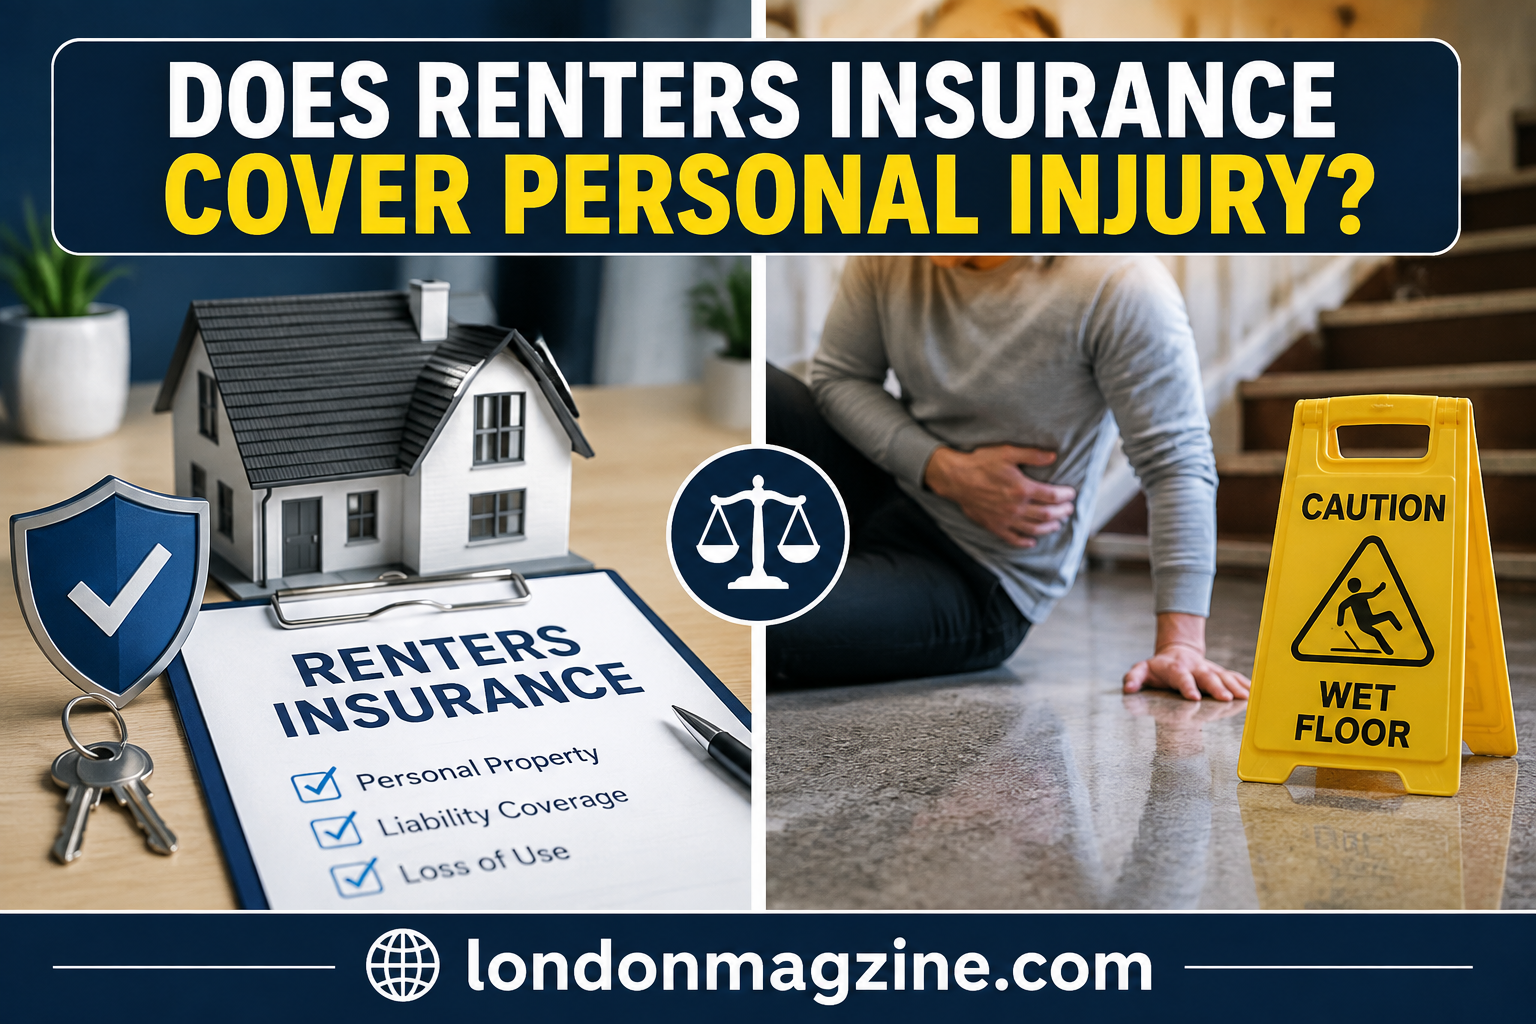
Renters insurance protects your belongings and offers liability coverage if someone gets hurt in your rental. Many people wonder exactly how far this protection reaches when personal injury claims arise. Understanding the details helps you know when you’re covered and when you might need extra steps.
What Renters Insurance Typically Includes
Renters policies focus on two main areas: personal property and liability. Personal property covers your belongings after events like theft or fire. Liability coverage steps in when you are responsible for someone else’s injury.
Core Parts of a Standard Policy
- Protection for your furniture, electronics, and clothes
- Temporary living expenses if your rental becomes unlivable
- Legal defense costs if a guest sues you
Does Renters Insurance Cover Personal Injury?
Yes, renters insurance covers personal injury through its liability section in many common situations. This part pays for medical bills and legal fees when someone claims you caused their injury inside your home.
Coverage usually applies if a guest slips on a wet floor you just mopped or gets hurt by a falling object you own. The policy pays up to your chosen limit, often starting at $100,000.
Situations Where Coverage Applies
- A visitor trips over loose carpet in your living room
- Your pet causes minor harm during a supervised visit
- Someone is injured by an item you stored improperly
When Coverage Does Not Apply
Liability protection has clear limits. It does not cover injuries to yourself or damage you cause on purpose. It also excludes injuries that happen outside your rental unit, such as at a neighbor’s place.
Key Exclusions
- Your own medical bills
- Intentional acts or illegal activities
- Injuries from business activities run from the rental
- Damage caused by certain dog breeds in some policies
Covered vs Not Covered Comparison
| Situation | Covered by Liability? | Notes |
|---|---|---|
| Guest slips on wet floor you mopped | Yes | Medical bills and legal costs paid |
| You injure yourself in the kitchen | No | Your own injuries not included |
| Injury during a home business meeting | No | Business use requires separate policy |
| Neighbor’s child hurt at your door | Yes | If incident occurs on your rented property |
| Intentional damage you caused | No | Policy will not pay |
How Much Liability Coverage Should You Choose?
Most experts suggest at least $300,000 in liability protection. Higher limits cost only a small extra premium each month but protect your savings and future wages if a large claim occurs.
Tips to Strengthen Your Protection
- Review your policy limits once a year
- Ask about adding pet liability if you have animals
- Keep records of safety improvements like non-slip mats
- Bundle with auto insurance for possible discounts
5 FAQs
Does renters insurance cover personal injury from a dog bite?
Most policies cover dog bites that happen inside your rental, but some breeds may be excluded. Check with your insurer.
Will my policy pay if a guest damages my property?
No. Liability covers injuries to others, not damage they cause to your belongings.
Can I use renters insurance for injuries at the building’s common areas?
Usually not. Coverage applies only inside your rented unit unless the policy states otherwise.
Does renters insurance cover personal injury if I rent a room in a shared house?
It depends on the policy. Some cover only the space you rent exclusively.
How soon should I report an injury claim?
Report any incident right away, even if it seems minor. Quick notice helps the claims process move smoothly.
Renters insurance offers solid protection against personal injury claims when you understand its liability benefits and limits. Choosing the right amount of coverage keeps you prepared for unexpected situations.

Leave a Reply